Market downturns can be unsettling, even for experienced investors. Whether triggered by a pandemic, rising inflation, geopolitical tensions or economic uncertainty, sharp share market falls often lead investors to ask the same question: “Should I move to cash until things settle down?”
While moving to cash may feel like the safest option during periods of volatility, history shows that trying to time the market can significantly reduce your long-term investment returns.
During market downturns it’s natural to want to protect your portfolio from further losses. Behavioural finance refers to this as loss aversion, the tendency to feel losses more strongly than gains. While the instinct is understandable, acting on those emotions can make it harder to achieve your long-term investment goals.
Why market timing rarely works
For even the most seasoned of investors, watching the value of your investments decline is never easy.
When share markets fall sharply, emotions can take over and feelings of fear, panic and discomfort can set in. Minimising further losses and moving to cash can seem like the best, most logical thing to do. Even if that means abandoning your investment plan which had carefully considered your long term goals, comfort with risk and time horizon.
It’s important to think about the consequences and how this may impact your future.
Selling investments is only half the decision.
The much harder question is knowing when to invest again. Missing just a handful of the market’s strongest recovery days can have a significant impact on your long-term returns.
History shows that some of the market’s strongest daily gains occur shortly after its biggest declines. This happened during the 1987 share market crash, the Global Financial Crisis, the COVID-19 market sell-off and more recent periods of volatility. Investors who moved to cash often missed these powerful recovery days, making it difficult to catch up later.
If you miss out on two days when the market rises 5% because you’re in cash, that could be a whole year worth of returns you’ve foregone.
The opportunity cost of staying in cash
It’s fair to say, moving to cash will offer some level of comfort in the short term, knowing your money is in a bank account where it won’t decrease in value any further (or so you think).
While cash protects you from short-term market falls, it also limits your ability to benefit from market recoveries. Over long periods, shares have historically delivered higher returns than cash, although with greater short-term volatility.
The chart below compares different investing strategies during the Global Financial Crisis (GFC) of 2007-2009.
It shows the growth of a $100,000 portfolio invested in over the next ten years based on three different choices you could have taken.
1) Stay invested in the share market through the GFC and the following 10 years
2) Exit the share market in January 2009 (when the portfolio had fallen to approximately $50,000), and then re-enter one year later
3) Exit the share market in January 2009 (when the portfolio had fallen to approximately $50,000), and stay in cash for the next 10 years
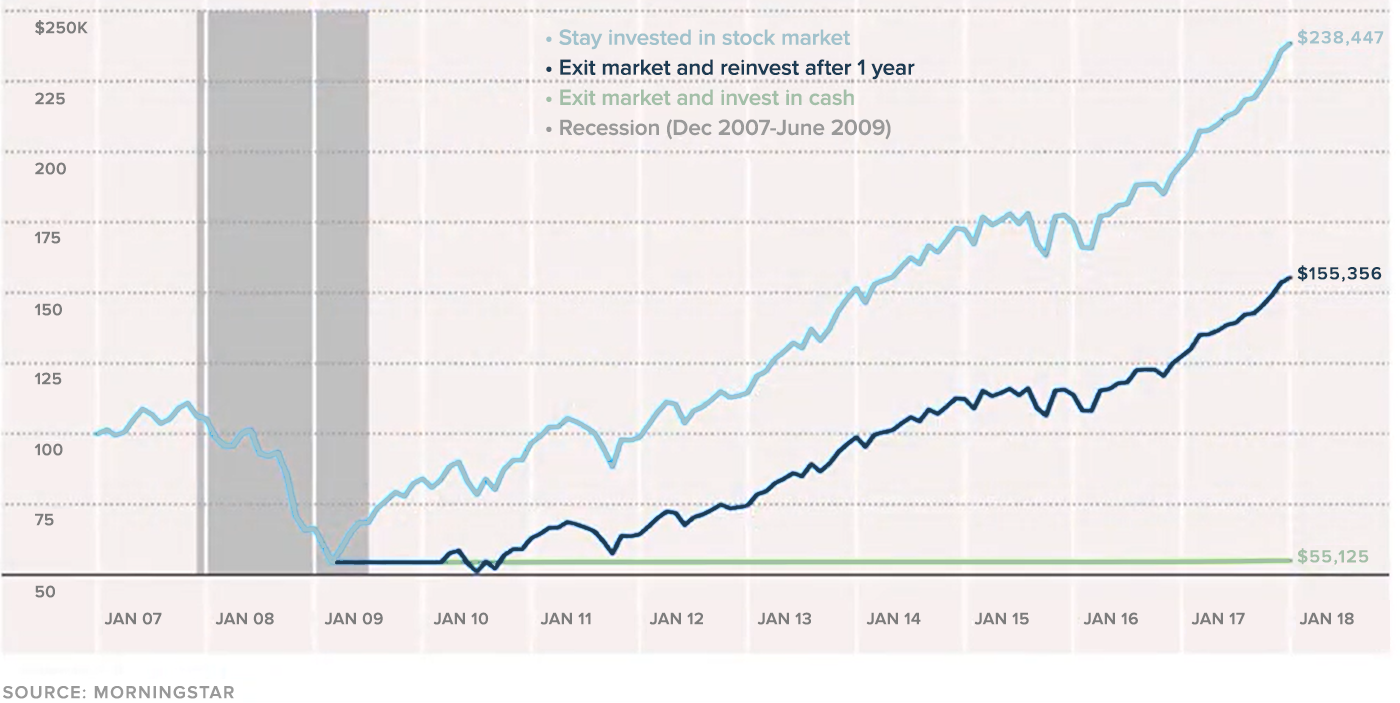
The chart illustrates a common investing lesson: the longer investors remain out of the market, the harder it becomes to recover lost ground. Remaining invested through periods of volatility has historically produced stronger long-term outcomes than attempting to time the market.
An investor who moved to cash during the crisis and stayed there for the next 10 years (green line), would have seen their $50,000 portfolio grow to just $55,125.
If you waited it out a year for markets to settle down you would have ended with $155,356.
Meanwhile an investor who did absolutely nothing and rode out the market volatility would have ended with $238,447, a return of 375%.
The results were similar after the 1987 crash, showing that moving to cash after a large market correction can be an expensive mistake over the following years.
The impact of tax and transaction costs
There’s another reason you might want to reconsider moving to cash – tax.
From a tax perspective selling investments may also trigger capital gains tax if your investments have increased in value. Depending on your circumstances, this could reduce the amount available to reinvest when markets recover. Frequent buying and selling may also increase brokerage costs and reduce after-tax returns over time. Any money you pay in tax now is money that isn’t invested and compounding for you.
A whitepaper by BOS Invest shows investors who move in and out of the market lose an additional 0.6% p.a. in returns due to tax and transaction costs.
This table shows the impact of staying in cash over different periods of time during the year.
| Percent of time period invested in cash | Loss in Annual Return before tax and transaction costs | Loss in Annual Return after tax and transaction costs |
| 5% | 0.23% | 0.83% |
| 10% | 0.46% | 1.06% |
| 15% | 0.69% | 1.29% |
| 20% | 0.93% | 1.53% |
| 25% | 1.11% | 1.71% |
| 30% | 1.31% | 1.91% |
| 35% | 1.54% | 2.14% |
When moving to cash does make sense
Moving to cash isn’t always the wrong decision. It may be appropriate if:
- you’re investing money you’ll need within the next few years
- your financial circumstances have changed
- your emergency savings are inadequate
- your investment strategy no longer matches your risk tolerance
- you’re deliberately reducing risk as you approach retirement
The key difference is making these decisions as part of a long-term financial plan, not in response to short-term market movements.
Key takeaways
- Market downturns are a normal part of investing.
- Trying to time the market is extremely difficult, even professional investors struggle to do it consistently.
- Missing the market’s strongest recovery days can significantly reduce long-term returns.
- Moving to cash may also create tax consequences and additional transaction costs.
- Review your investment strategy regularly, but avoid making decisions based solely on short-term market movements.
Successful investing isn’t about predicting every market movement, it’s about having a strategy that you can stick with through changing market conditions. A diversified portfolio aligned with your goals and risk tolerance can help you stay invested when markets become volatile.
If you’re unsure whether your investment strategy still suits your circumstances, consider reviewing your portfolio before making significant changes. The Stockspot Goal Tracker is one way of doing just that.
Frequently Asked Questions
Should I move my investments to cash during a market crash?
While every situation is different, history suggests investors who remain invested have generally achieved better long-term outcomes than those attempting to time the market.
Is cash safer than shares?
Cash generally experiences less short-term volatility than shares, but over the long term it has historically delivered lower returns and may lose purchasing power to inflation.
Can I lose money by staying invested?
Yes. Share markets fluctuate and can fall significantly over short periods. However, historically, diversified investors with long investment horizons have typically recovered from market downturns.
How often should I review my investment strategy?
Review your investment strategy when your goals, financial circumstances or risk tolerance change – not simply because markets become volatile.
Disclaimer: The content of this website is not intended to represent or be a substitute for specific taxation or legal advice and should not be relied on as such. Any taxation, legal and other matters referred to are based on Stockspot’s interpretation of existing laws and should not be relied upon in place of appropriate professional advice. Those laws may change from time to time.